Insurance sign up checklist: Why review coverage details now
"The fine print is often where the reality of a contract lives, far away from the glossy brochures and sales pitches."
Securing an insurance policy requires a meticulous review of terms, coverage limits, and legal obligations to ensure long-term protection.
This guide explores the essential steps for an insurance sign up checklist, including understanding regulatory frameworks, verifying coverage scope, and identifying potential bureaucratic hurdles.
You will learn to navigate complex policy terms, recognize the importance of legislative oversight, and prepare for specific administrative requirements.
How do I begin my insurance sign up checklist?
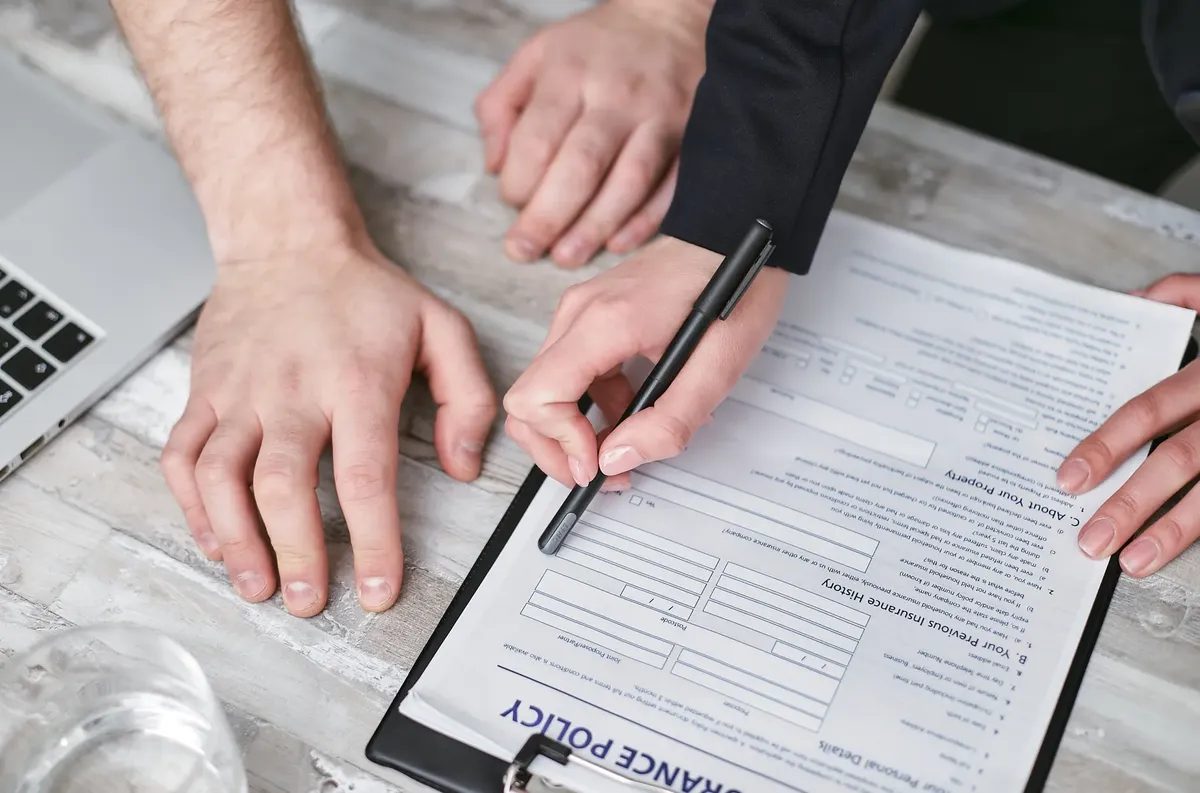
At midnight in the silent study, my fingers tremble as I gather scattered papers to start my insurance sign up checklist.
A hand reaches for a thick folder of documents sitting on a mahogany desk. Before signing any document, you must establish a clear understanding of the regulatory environment and the specific market you are entering.
An insurance sign up checklist should always begin with verifying the legitimacy and regulatory standing of the provider.
For instance, historical context shows that specific departments, such as the New York State Insurance Department (NYID) in 1999, have issued guidance to facilitate market participation for specific types of insurers.
Understanding these historical regulatory shifts helps you recognize how modern oversight affects your coverage.
You should also look at the scale of the industry to understand market stability. According to the Association of British Insurers, which groups together 400 insurance companies and 94% of UK insurance services, the industry represents a massive portion of market investments.
This scale indicates that while the market is vast, individual policies are subject to specific, localized rules that you must identify before committing.
- Gather all personal identification and existing policy documents.
- Define your primary insurance needs and budget.
- Research potential providers and comparison tools.
What are the key insurance checks for coverage scope?
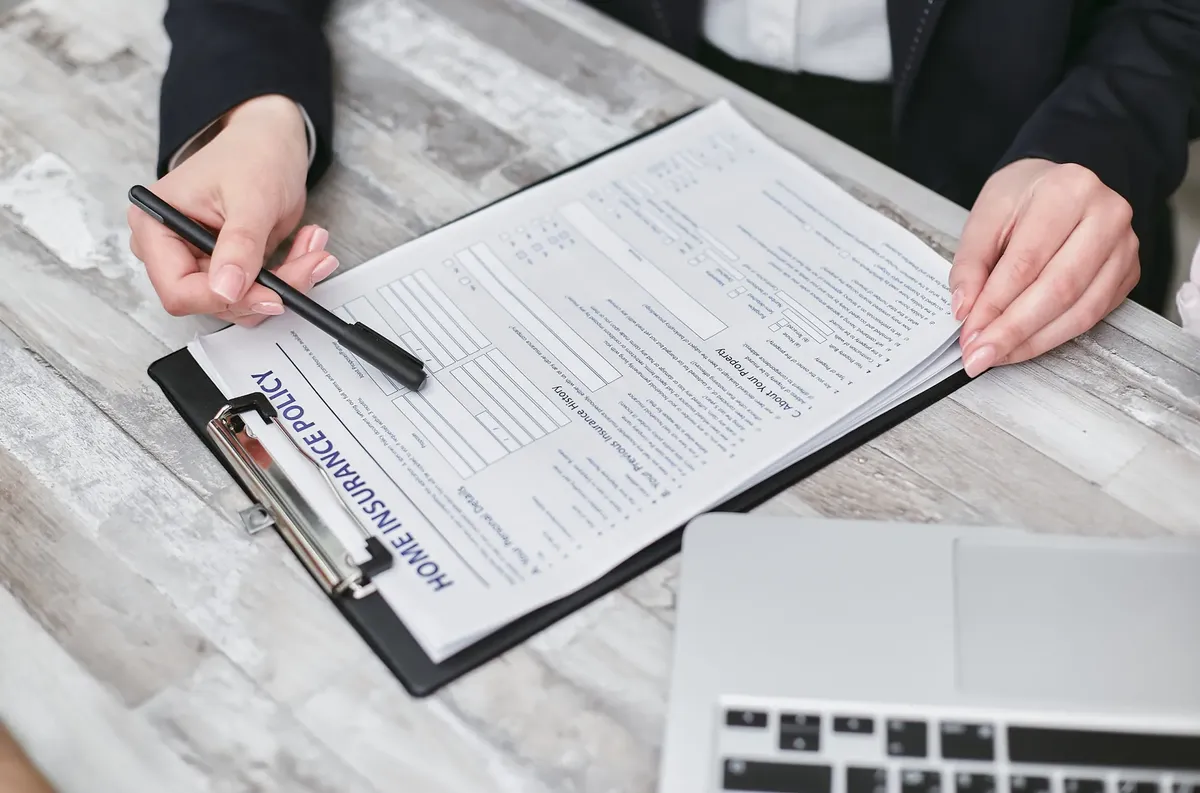
A pen hovers over a line item in a contract while an agent waits patiently. You must move beyond the surface level to understand exactly what is being protected and what falls into the category of exclusions.
Understanding the specific type of insurance is vital because different products serve vastly different legal and financial functions. For example, standardized forms of title insurance exist specifically for owners and lenders to mitigate risks during property transfers.
Before insurance purchase, you must determine if your current needs align with these standardized industry forms or if you require something more specialized.
In some cases, the documentation might mention complex certification processes. A 2007 book discussing the American title insurance industry acknowledged that more extensive use of Torrens certification would require setting up a special judicially supervised bureaucracy.
When you review your policy, check if your coverage relies on such specialized administrative processes, as this can affect how claims are handled.
In this sequence, the second step is the most extensive.
How can I understand policy terms fully?
Late at night in the quiet library, my fingers trace the heavy paper as I struggle to grasp the complex insurance terms.
A magnifying glass moves slowly across a page of dense, legalistic text. To avoid surprises, you must dissect the language to ensure the definitions used in the policy match your real-world expectations.
A 2007 book attacking the American title insurance "cartel" acknowledged that "[m]ore extensive use of Torrens certification would require setting up a special judicially supervised bureaucracy," according to cartel.
The relationship between different financial instruments and insurance can be complex.
In 1999, the New York State Insurance Department (NYID) issued guidance regarding insurance of obligations under credit default swaps, which facilitated the participation by financial guaranty insurers in the CDS market.
This shows how specific guidance can change how insurers interact with complex financial products.
When you review coverage details now, look for how "obligations" and "guarantees" are defined. You need to know if a policy is designed for simple risk transfer or if it involves complex financial market participation.
If you are dealing with specialized products, the terms may be much more technical than standard life or health insurance.
How do I calculate insurance costs first?
A calculator sits next to a stack of monthly budget sheets. You must balance the cost of premiums against the value of the coverage to ensure the policy is sustainable for your financial future.
Legislative changes often dictate the cost and availability of insurance products through various reform acts.
For example, the primary legislative responses to a crisis were the Financial Institutions Reform, Recovery and Enforcement Act of 1989 (FIRREA) and the Federal Deposit Insurance Corporation Improvement Act of 1991 (FDICIA).
These types of laws can influence the capital requirements of insurers, which ultimately affects your premium rates.
To manage these costs, follow these steps: 1. Identify the exact scope of coverage required for your specific asset or life stage. 2. Compare the premium costs against the potential payout to evaluate the risk-to-reward ratio. 3.
Check for any mandatory fees or administrative costs that might be hidden in the fine print. 4. Verify the final total against your long-term budget to ensure you can maintain the policy.
What should I look for in an insurance policy review?
A person sits quietly in a sunlit room, comparing two different policy documents side by side. A thorough review involves comparing the stability of the provider with the specific protections offered in the contract.
| Feature | Standardized Title Insurance | CDS-Related Insurance |
|---|---|---|
| Primary User | Owners and Lenders | Financial Guaranty Insurers |
| Context | Property Ownership | Credit Default Swaps |
I noticed during my own review that comparing these two distinct types of coverage requires a different mindset for each. While one protects physical assets, the other protects financial obligations.
One limitation of this checklist is that it cannot account for sudden, localized changes in law that occur after you sign your contract.
While the primary legislative responses like FIRREA and FDICIA set the stage for institutional stability, individual policy terms are subject to the specific oversight of the jurisdiction where the policy is issued.
The same subject is also called What to check before.
Related
Comments 0